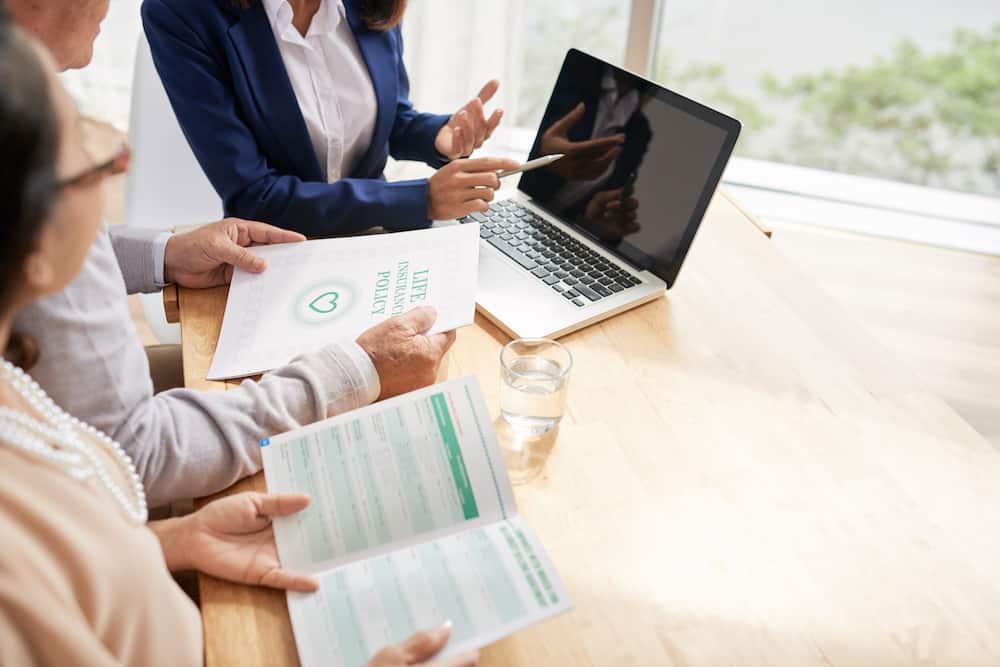
Whole life insurance is a great way to provide lifetime protection with added benefits. In addition to providing you with lifetime coverage, whole-life policies offer the opportunity for growth in cash value that can be used tax-deferred. This cash value could be used for the future - whether towards your retirement or student loans. There's no reason not to get protected with Whole Life Insurance with all these benefits at hand. Let's take a better look at Whole Life Insurance.
What Is Whole Life Insurance?
Whole life insurance is a life insurance policy that provides permanent death benefit coverage for the insured. In addition to paying a death benefit, whole life insurance also contains a savings component in which cash value may accumulate on a tax-advantaged basis. Thus, it may also be known as "traditional" life insurance.
Understanding Whole Life Insurance
Whole life insurance is a type of contract where the policyholder pays regular premiums in exchange for death benefits. The cash value component provides additional savings opportunities and accumulates on a tax-deferred basis. Therefore, growing cash value is an essential component of whole life insurance.
Using the Cash Value
You can tap into the cash value with either a withdrawal or a loan. Loans are tax-free, and you can pay them back with interest. If you make a withdrawal, there are no taxes as long as your withdrawal is less than the part of your cash value, attributable to premiums you've paid. If your withdrawal is more significant, you'll owe taxes on the difference as they are investment gains.
Picking Life Insurance Beneficiaries
When you buy a policy, you'll choose a life insurance beneficiary to receive the death benefit. You don't have to split the payout equally among beneficiaries. It's also a good idea to also designate one or more contingent beneficiaries. They can act as backups in case all the primary beneficiaries are deceased when you pass away.
What Happens When You Die
Whole life insurance will be in force until your death, unlike term life insurance. You can't outlive the whole life policy as long as you've paid the premiums. The policy will only pay out the death benefit for most policies, no matter how much cash value is accumulated. At your passing, the cash value will revert to the insurance company. Outstanding loans and past withdrawals from cash value will still reduce the payout to your beneficiaries.
Factors affecting your eligibility and costs
The coverage amount you choose will help determine your rate, along with:
- Age and gender
- Height and weight
- Past and current health conditions
- The health history of your parents and siblings
- Nicotine and marijuana use, including nicotine patches and gum
- Substance abuse
- Credit
- Criminal history
- Driving record
- Dangerous hobbies and activities
Benefits of Whole Life Insurance
The cost will stay the same
Your premium is guaranteed not to go up for the duration of your life insurance policy. This makes this type of life insurance more affordable in the long run.
Fixed benefits
Your beneficiaries will receive a fixed amount from your death benefit. It'll guarantee a problem-free life for them even after you're gone.
Tax-advantages benefits
In addition to the tax-free sum, you'll be leaving it to your loved ones. Your cash value will grow on a tax-deferred basis. You can borrow against the cash value if you need a loan (you can pay the money back or reduce the amount going to your beneficiaries).
Potential Dividends
If you buy a whole life insurance policy, you may receive annual dividend payments on it. These payments, while not guaranteed, are a way to share with the policyholder. You can then reinvest dividends into your policy to help build cash value faster.
The future is uncertain, but with whole life insurance, you can set up a stable retirement for your loved ones. Whole life policies are designed to cover the costs of funeral expenses in addition to any other living needs that might arise, like tuition or medical care after an accident. In addition, a guaranteed death benefit means there's no risk of losing money in the event of an unfortunate circumstance. This kind of protection allows families not only peace of mind knowing everything will be taken care of financially — leaving them free from worry about financial security in the long term.