Winter driving can bring unpredictable challenges, from icy roads and heavy snowfall to poor visibility and unexpected vehicle damage. Even experienced drivers may find themselves dealing with accidents, fallen tree branches or roadside breakdowns during colder months. While preparing your vehicle for winter is important, reviewing your car insurance coverage is equally valuable. Understanding what your policy covers can help you handle unexpected expenses and drive with greater confidence.
1. Understand How Collision Coverage Protects You
Snow-covered roads and icy surfaces can make it harder to control your vehicle, increasing the risk of accidents. Collision coverage can help pay for repairs to your car if it collides with another vehicle or an object, regardless of who is at fault, subject to your policy terms and deductible. If you live in an area that experiences frequent winter storms, reviewing your collision coverage and deductible can help you prepare for potential repair costs.
2. Check Your Comprehensive Coverage
Winter weather can damage your vehicle in ways that do not involve a collision. Falling tree branches, hail, certain types of storm damage and flooding may be covered under comprehensive insurance, depending on the circumstances and policy exclusions. This coverage can be particularly useful when your car is parked outdoors or exposed to severe weather. Review your policy to understand which weather-related events are covered and what deductible applies.
3. Consider Roadside Assistance Coverage
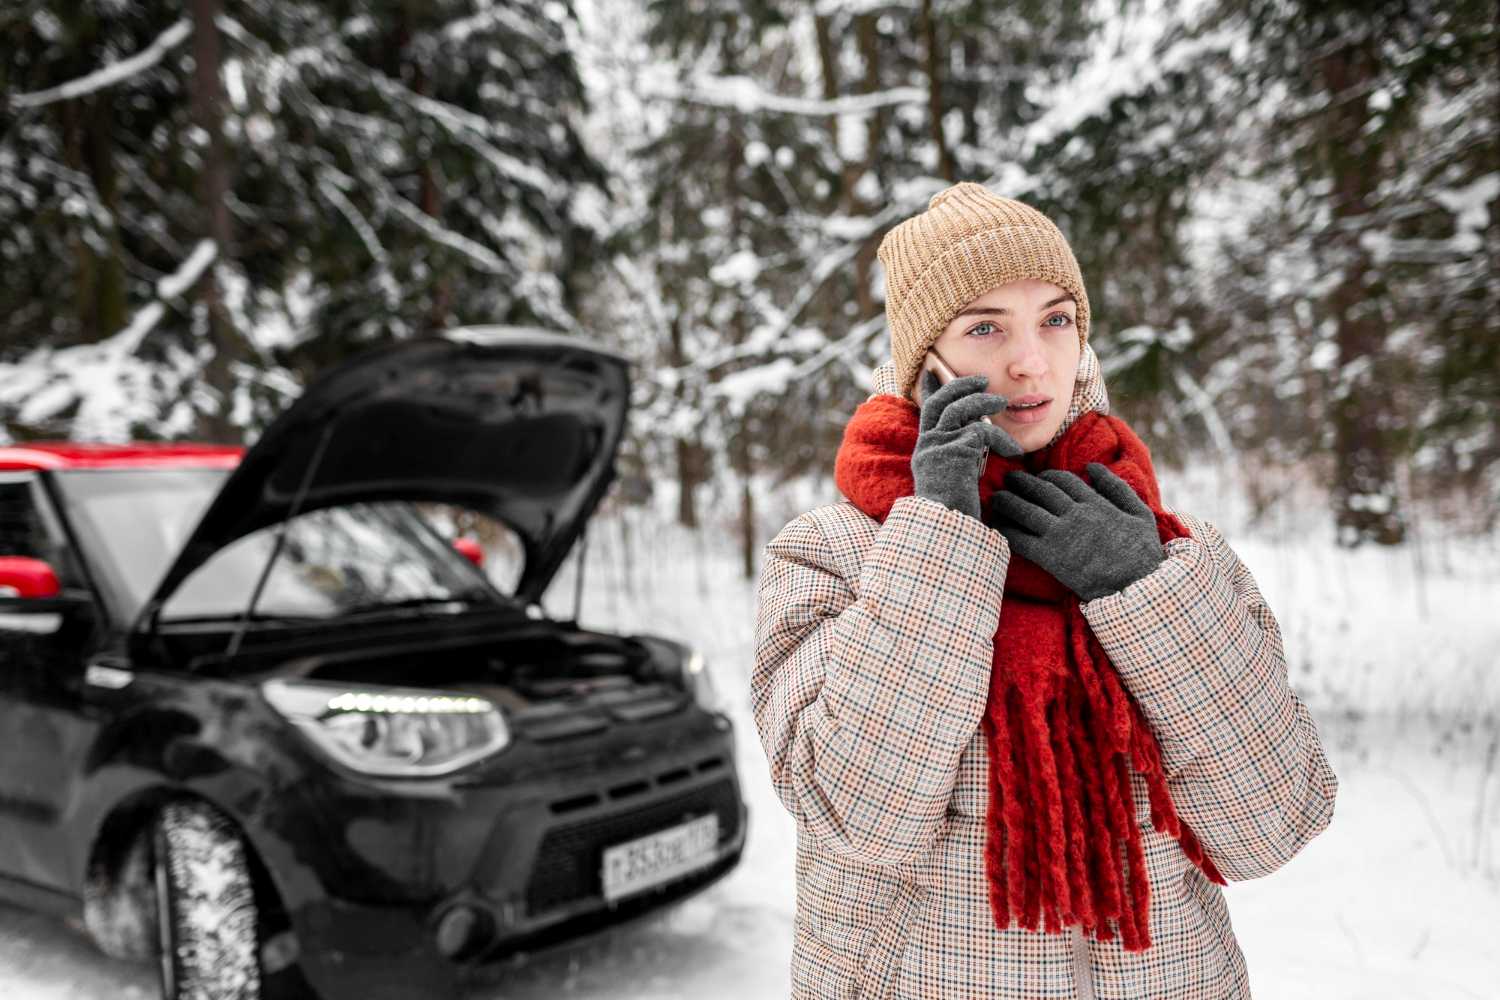
A dead battery, flat tire or vehicle breakdown can become especially inconvenient during freezing temperatures. Roadside assistance coverage may provide services such as towing, battery jump-starts, flat tire assistance and lockout support, depending on your plan. Check whether this benefit is included in your policy or available as an optional add-on, and understand any service limits or restrictions before relying on it.
4. Review Your Rental Car Reimbursement Benefits
If your vehicle needs repairs following a covered accident, you may need alternative transportation while it is in the repair shop. Rental reimbursement coverage can help pay for a rental vehicle during an eligible repair period, subject to daily and overall coverage limits. This can be particularly helpful during winter when getting to work, school or essential appointments may be difficult without a car.
5. Check Your Deductibles and Coverage Limits
Your deductible is the amount you generally pay out of pocket before your insurer pays an eligible claim. A higher deductible may lower your premium, but it also means you will need to contribute more toward covered repairs. Review your comprehensive and collision deductibles, liability limits and other coverage details to make sure they fit your financial situation. Choosing coverage solely based on a lower premium may leave you with greater expenses after an accident.
6. Know What Your Policy Does Not Cover
Not every winter-related vehicle problem is covered by car insurance. Mechanical breakdowns caused by normal wear and tear, routine maintenance issues and certain types of damage may be excluded. For example, a weak battery that stops working because of age is generally a maintenance issue rather than a comprehensive insurance claim. Understanding exclusions can help you distinguish between situations that require an insurance claim and those that need professional auto repair.
Winter driving requires both vehicle preparation and financial protection. By reviewing collision and comprehensive coverage, checking roadside assistance benefits and understanding your deductibles, you can make more informed decisions about your insurance needs. A quick policy review before the colder months can help you identify coverage gaps and prepare for unexpected situations on the road.